
Consumer Proposal Windsor
A consumer proposal can cut your unsecured debt by up to 80%, stop creditor calls the day it’s filed and let you keep your home and car.
Our Licensed Insolvency Trustees help people across Windsor, from downtown and Walkerville to Riverside, Sandwich and South Windsor, with free, confidential consultations by video or phone.
The sooner you act, the more options you have.
Safe, secure & confidential


How does a consumer proposal work in Windsor?
A consumer proposal in Windsor works through a Licensed Insolvency Trustee (LIT), who files a legally binding offer to your creditors to repay part of your unsecured debt. It can cut what you owe by up to 80%, and the federal Bankruptcy and Insolvency Act sets the same rules across Canada.
You make one fixed, interest-free monthly payment for up to five years and keep your home, car and other assets. Once your trustee files, collection calls, interest charges and wage garnishments stop.
Who qualifies for a consumer proposal in Windsor?
You qualify for a consumer proposal if you owe between $1,000 and $250,000 in unsecured debt and can’t repay it in full but can afford a regular monthly payment.
You also need to:
- Be an individual, not a corporation.
- Live in Canada or own property in Canada.
- Be at least 18 years old.
The $250,000 limit excludes your mortgage. If you don’t qualify, see our other debt relief options in Windsor, or we will assess your situation for free.
What do clients say about our consumer proposal service?
Clients rate Harris & Partners 4.8 out of 5 from more than 2,200 Google reviews and “Excellent” on Trustpilot, for clear advice and judgment-free support.


Based on OSB data, nearly 3 in 4 people in Windsor choose a consumer proposal over bankruptcy.
Among those facing insolvency, it's how most clear debt and keep their home.
Among those facing insolvency, it's how most clear debt and keep their home.

Consumer proposal vs bankruptcy vs debt consolidation: Which is right for you?
A consumer proposal in Windsor reduces your debt while you keep your assets, bankruptcy clears more debt but may cost you assets, and debt consolidation is a new loan that doesn’t reduce what you owe.
The right choice depends on your income, assets, and total debt, and a trustee will walk you through all three.
| Consumer proposal | Bankruptcy | Debt consolidation | |
|---|---|---|---|
| Reduces debt? | Yes, up to 80% | Yes, most debt cleared | No |
| New loan needed? | No | No | Yes |
| Interest | 0% | 0% | Variable, often high |
| Stops collection calls? | Yes, on filing | Yes, on filing | No |
| Your assets | Keep all assets | May lose some assets | Keep all assets |
| Credit report | R7 until 3 years after completion or 6 years after filing, whichever comes first | R9 for 6–7 years after discharge (first bankruptcy) | Depends on repayment history |
| Government-regulated? | Yes | Yes | No |

How could a consumer proposal help you in Windsor?
A consumer proposal in Windsor could cut your debt, stop creditors chasing you, and let you keep your assets, all through one interest-free monthly payment.
- Reduce your debt by up to 80%: Creditors often accept significantly less than the full balance.
- Stop creditors the day you file: Collection calls and wage garnishments must stop, with legal protection under the Bankruptcy and Insolvency Act.
- Keep your home, car and other assets: You don’t surrender property, unlike in bankruptcy.
- One interest-free payment every month: Interest freezes on filing, and your trustee sets the payment around your budget, spread over up to five years.
- Qualify easily, with a high approval rate: There’s no credit check, and 9 in 10 proposals we file are accepted by creditors.

How to file a consumer proposal in Windsor
A consumer proposal in Windsor has four main stages, from a free consultation with a Licensed Insolvency Trustee to a Certificate of Full Performance once your payments and counselling are complete.
- 1. Book a free consultation: A trustee reviews your debts, income and assets and explains every option, not just consumer proposals. It takes under an hour, and you have no obligation to commit.
- 2. Draft and file your proposal: If a proposal suits you, we prepare it with a monthly payment you can afford and file it with the Office of the Superintendent of Bankruptcy. Collection calls, interest and wage garnishments stop immediately.
- 3. Creditors vote: Creditors have 45 days to respond. If creditors holding the majority of your debt by value accept, the proposal binds all of them.
- 4. Make your payments and finish the program: You pay your trustee once a month for up to five years and attend two financial counselling sessions. After your last payment, you receive a Certificate of Full Performance and the included debts are cleared.
Why choose Harris & Partners for your consumer proposal in Windsor?
We’ve helped Canadians get out of debt since 1964, with plain-English advice from people who care about your financial stability. There are no intimidating offices and no legal jargon.
We’re one of Canada’s largest insolvency filers, with more than 100 years of combined trustee experience and long-standing creditor relationships that help get proposals approved.
Windsor residents who file with us can legally reduce their unsecured debt by up to 80% and repay the rest in affordable instalments.

Why choose Harris & Partners for your consumer proposal in Windsor?
How much could you save with a consumer proposal?
In this example, a consumer proposal cuts monthly repayments on $38,290 of debt from $1,409 to $210 over 60 months.
Repayments over 60 months

Before help
$1,409
After help
$210
Example only; your payment depends on your income, assets and debts.
Estimate your monthly payment
What types of debt are covered by consumer proposals in Windsor?
A consumer proposal can include most unsecured debts, combining them into one interest-free monthly payment:
- Credit cards – balances across any number of cards
- Payday loans – ending the borrowing cycle
- Personal loans and lines of credit – from banks or private lenders
- CRA tax debt – income tax arrears, GST/HST you owe personally and CERB overpayments
- Student loans – once seven years have passed since you left school
- Medical bills and utility arrears – including unpaid hydro and gas
Mortgages and car loans are secured debts, so they stay outside the proposal. Filing does stop wage garnishments from your unsecured creditors, which makes it easier to keep up those secured payments.
Where is our nearest office to Windsor?
Our nearest office to Windsor is in Brantford, at:
446 Grey St, Suite 110, Brantford, ON N3S 7L6.
Because it’s a long drive, most Windsor clients meet their trustee by video or phone.
Meet your Licensed Insolvency Trustee
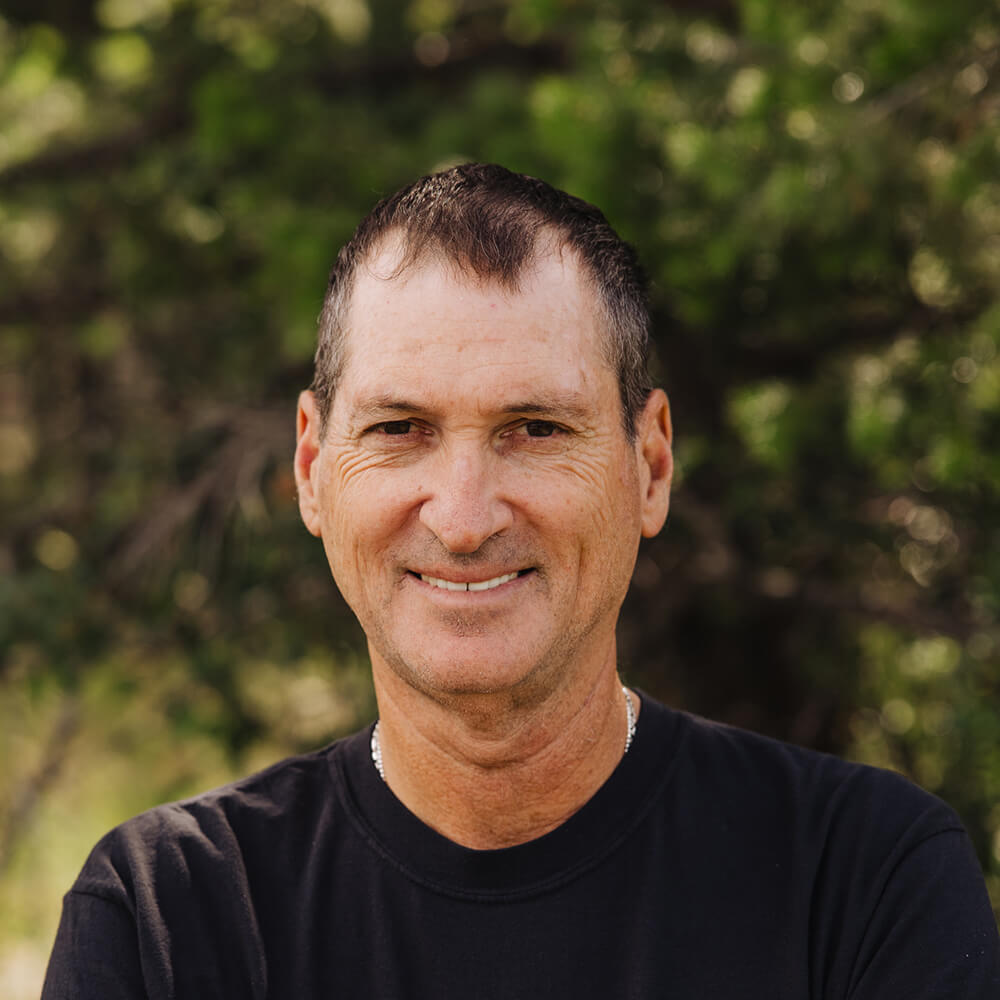
Jay Harris is Managing Partner of Harris & Partners and a Licensed Insolvency Trustee.
He has been with the family firm since 1982, qualified as a Chartered Accountant in 1984 and became a founding partner of Harris & Partners Inc. in 1987.
He’s a Fellow of Chartered Professional Accountants Ontario (FCPA, FCA) and a Chartered Insolvency and Restructuring Professional (CIRP)
Address
446 Grey St, Suite 110, Brantford, ON N3S 7L6
How to get there
By car: Take Highway 401 east to Woodstock, then Highway 403 east to Brantford. (The drive takes about 2.5–3 hours.)
By train: VIA Rail runs between Windsor and Brantford on its Windsor–Toronto route.
For most Windsor clients, a video or phone consultation is quicker and easier.
Office hours
Monday to Friday: 09:00-17:00 (by appointment only)
Windsor consumer proposal FAQs
These answers cover the questions Windsor residents ask most about consumer proposals, from tax debt and credit ratings to cost.
Do I have to travel to an office for a consumer proposal in Windsor?
You can handle a consumer proposal in Windsor without visiting an office; meeting your trustee by video or phone is the most common choice, so there’s no need to travel to Brantford. The same applies across Essex County, including LaSalle, Tecumseh, Amherstburg and Leamington, and the first consultation is free with no obligation.
Do I need a lawyer for a consumer proposal in Windsor?
You don’t need a lawyer for a consumer proposal in Windsor; a Licensed Insolvency Trustee prepares it and files it with the Office of the Superintendent of Bankruptcy. Once creditors accept it, the court treats it as approved after 15 days, so you only face a hearing if the official receiver or another interested party requests a review.
How much of my debt will I repay in a consumer proposal in Windsor?
Most people repay between 20% and 40% of their unsecured debt through a consumer proposal in Windsor, spread over up to five years. The exact amount depends on your income, essential living costs, household size and assets, and the trustee’s federally set fees come out of those payments, so there’s nothing to pay upfront.
Can I include GST/HST debt in a consumer proposal in Windsor?
You can include GST/HST you owe personally, for example as a sole proprietor, in a consumer proposal in Windsor, along with personal income tax and CPP or EI overpayments. These CRA debts are combined with your credit cards and loans, the CRA votes like any other unsecured creditor, and filing stops CRA garnishments and bank account freezes.
What does an R7 rating mean after a consumer proposal in Windsor?
An R7 rating shows lenders that you’re settling debts through a consumer proposal in Windsor, and it’s less severe than the R9 given for bankruptcy. Credit bureaus remove it three years after your final payment or six years after filing, whichever comes first, and most people’s scores begin recovering once payments are steady.